

How Does the EU CBAM Affect Manufacturing Companies in Vietnam?
From 1 January 2026, the EU Carbon Border Adjustment Mechanism (CBAM) entered its definitive phase. For certain imported goods, carbon obligations are linked to the emissions generated during production. In the EU, the authorised CBAM declarant is responsible for submitting the required declaration and surrendering the corresponding number of CBAM certificates in accordance with the applicable rules.
As non-EU manufacturers, companies in Vietnam have a different role from authorised CBAM declarants. Their responsibilities may involve providing emissions information, allocating internal resources, and coordinating with customers and suppliers when supplying goods within the relevant CBAM scope. This article explains these impacts and outlines the key areas manufacturers should prepare for.
Which Manufacturing Companies in Vietnam Should Pay Attention to CBAM?
A company’s relevance to CBAM depends on the type of goods, the applicable CN code, and its position in the supply chain.
1. Goods from Six Sectors Fall Within the CBAM Scope
CBAM currently covers certain goods in the following sectors:
| Sector | What to Check |
| Cement | Product type and corresponding CN code |
| Iron and steel | Iron, steel, and related products included in the relevant list |
| Aluminium | Aluminium types and aluminium products within scope |
| Fertilisers | Types of fertilisers and related goods |
| Electricity | Cases where electricity is imported into the EU |
| Hydrogen | Hydrogen covered by the specified commodity codes |
Operating in one of these sectors alone does not determine CBAM applicability. The scope should be assessed for each specific product against the CN codes listed by the EU.
2. Manufacturers of CBAM Goods in Vietnam
The companies most directly concerned are facilities in Vietnam that manufacture CBAM goods imported into the EU, whether the goods are sold directly or through an intermediary.
The emissions data used for CBAM is linked to the facility where the goods are actually produced. This remains relevant when products are sold through a trading company, parent company, or other intermediary.
3. Precursor Suppliers May Also Be Involved
A company may be asked to provide information when its products are used as precursors under CBAM in the production of other goods covered by the mechanism.
This may also apply where the company supplies the precursor to another manufacturer rather than exporting the finished goods to the EU itself.
The level of relevance depends on the precursor type, the downstream goods, and the applicable emissions calculation methodology.
How Does CBAM Affect Manufacturing Companies in Vietnam?
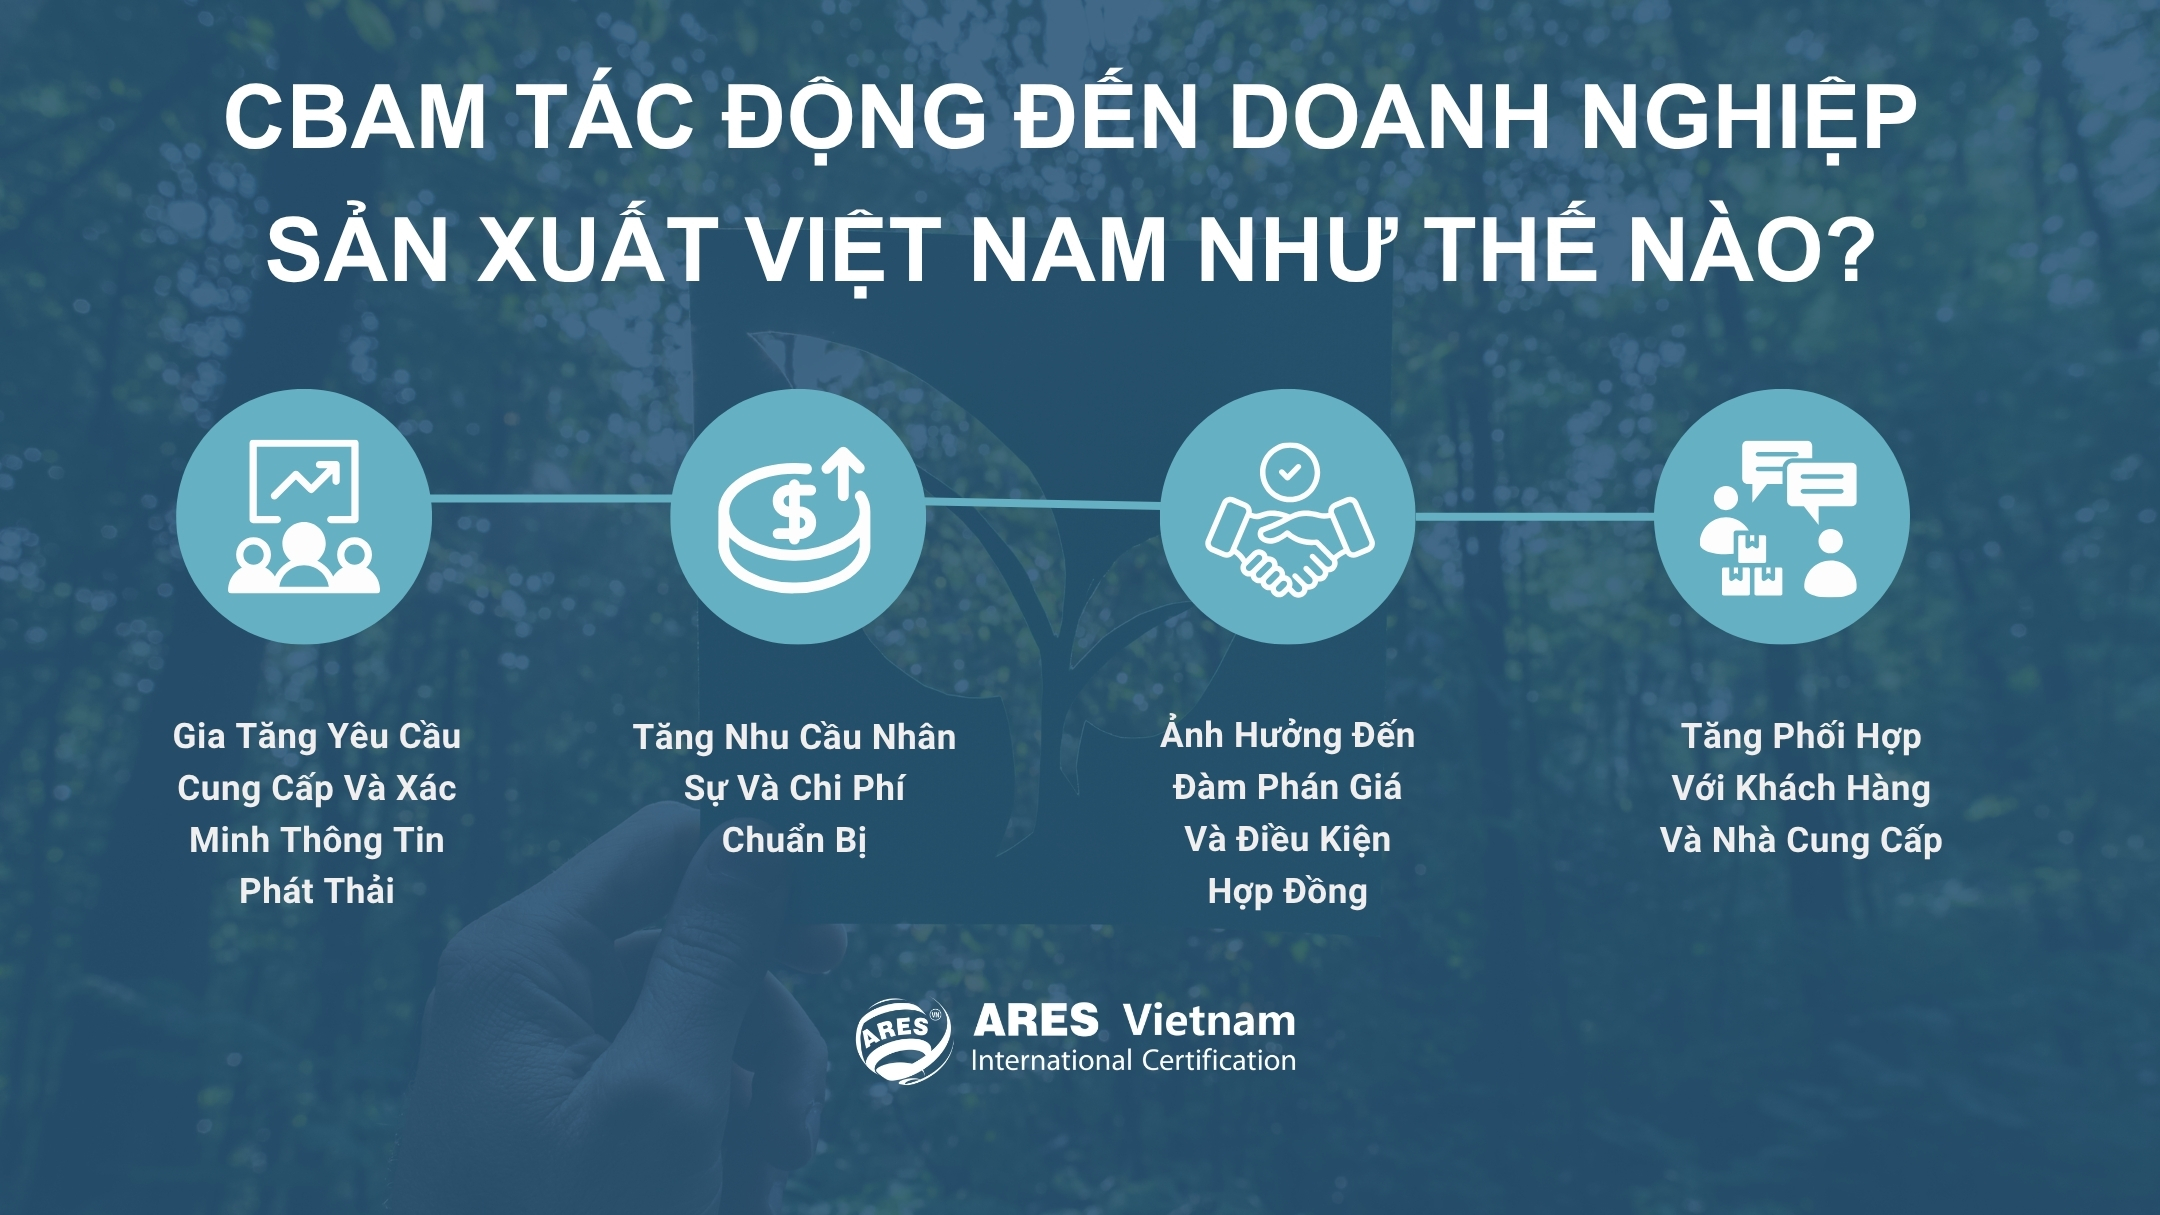
For factories producing CBAM-related goods, the impact may arise in four main areas:
1. Greater Requirements for Emissions Information and Verification
EU customers may request emissions information by installation, product, and production process.
A corporate-level greenhouse gas inventory may provide only part of the required information. Therefore, factories may need to supplement existing data or allocate it according to the CBAM methodology.
When actual emissions data is used for CBAM declarations, the results must be verified by a verifier accredited for CBAM verification by a national accreditation body of an EU Member State, with an appropriate scope of accreditation.
In addition, calculated emissions data should be traceable to the methodology used, input data, and supporting source records.
2. Increased Staffing Needs and Preparation Costs
Factories may need to assign personnel to compile records, review data, perform calculations, and coordinate verification activities.
The need for additional metering equipment or management tools depends on the applicable requirements and the capability of the existing system.
Preparation costs at the factory level are separate from the cost of purchasing CBAM certificates borne by the authorised CBAM declarant in the EU. Therefore, companies should first assess existing gaps before deciding on further investment.
3. Impact on Price Negotiations and Contract Terms
CBAM-related costs on the importing side may become a factor in purchase price negotiations.
The extent of the impact on Vietnamese manufacturers depends on the product, the calculated emissions results, and the commercial arrangements between the parties.
ccordingly, the parties should clarify responsibility for providing information, submission deadlines, procedures for handling discrepancies, and cost allocation. The allocation of CBAM-related costs should be determined through the relevant commercial arrangements.
4. Greater Coordination with Customers and Suppliers
Where input materials are treated as precursors under CBAM, factories may need emissions information from the facilities that manufacture those materials.
Missing or delayed information may affect both the timing and the method used to determine the emissions of the final goods.
When products are sold through a trading company or parent company, the parties should agree on communication contacts, required information, and submission deadlines. This helps ensure that EU customer requirements reach the factory accurately while protecting commercially sensitive production information.
What Should Companies Prepare to Meet CBAM Requirements?
After identifying the relevant goods and the applicable CBAM emissions calculation approach, companies should review the required data, available sources, and information gaps through the following steps.
1. Identify the Required Data Categories
The data scope depends on the type of goods and the applicable CBAM methodology. At factory level, companies can begin by reviewing four main groups of data:
| Data Category | Information to Identify |
| Production | Products, production volumes, production processes, and monitoring period |
| Energy and emissions | Fuels, materials related to process emissions, electricity, heat, and other parameters required under the applicable methodology |
| Precursors | Relevant precursor quantities and the emissions information required |
| Calculation | Factors, calculation methodology, and allocation basis |
This provides a review framework rather than a fixed list for every factory. Only data that falls within the calculation boundary of the relevant goods needs to be incorporated into the CBAM data system.
2. Select Appropriate Data Sources
The same indicator may appear in an ERP system, production report, warehouse records, or accounting records. For CBAM purposes, the selected data source should be based on its accuracy, reliability, and suitability for the applicable monitoring methodology.
Where figures differ between sources, the company should reconcile the supporting records, identify the reason for the discrepancy, and document the treatment applied before using the data in calculations.
3. Assign Responsibilities Based on Existing Data Ownership
Responsibility should be linked to the departments that currently generate or manage each data source. For example, production volumes may be managed by the production department. Electricity and fuel data may sit with engineering or energy management teams. Precursor information may be held by procurement or supplier management functions.
Companies may also designate a central coordinator to consolidate and review information before it is shared with customers or other relevant parties.
When actual emissions data is used for CBAM purposes, these responsibilities should also be documented in a written monitoring plan, together with the installation and production process boundaries, monitoring methods, calculation approach, and relevant data controls.
4. Review Data Gaps Before Expanding the System
Once data sources and responsible persons have been identified, the available information can be grouped into three categories:
| Status | Recommended Action |
| Available and ready for use | Maintain the existing source and control method |
| Available but requires processing | Standardise, allocate, or supplement the supporting basis |
| Not yet available | Define an appropriate collection method |
The results of this review can help companies decide whether additional meters, revised forms, or new management tools are required. This approach allows investment to be aligned with an identified need before the system is expanded.
How Can Companies Use Existing Data and ISO Management Systems?
Some data and management mechanisms already available through existing ISO systems may support the preparation of CBAM information.
| Standard | Existing Information That May Be Used |
| ISO 14064-1:2018 | Identification of emission sources, activity data, quantification, and organisation-level greenhouse gas inventory records |
| ISO 14067:2018 | Product data, production process maps, and carbon footprint quantification records |
| ISO 14001:2026 | Assignment of responsibilities, operational control, monitoring and measurement, and environmental information management |
| ISO 50001:2018 | Energy use and consumption data, Energy Performance Indicators (EnPIs), and Energy Baselines (EnBs) |
These elements should be assessed against the relevant CBAM requirements before use. CBAM itself defines the applicable calculation methodology, data scope, and verification requirements. Existing ISO systems can therefore provide useful supporting data and management controls within that framework.
Frequently Asked Questions (FAQ)
| Question | Answer |
| Does the 50-tonne threshold apply directly to Vietnamese manufacturers? | The 50-tonne threshold applies to the total net mass of CBAM goods imported by each importer during a calendar year. It aggregates goods from four sectors: iron and steel, aluminium, cement, and fertilisers. The threshold therefore applies at importer level rather than separately to each sector or manufacturer. Electricity and hydrogen are treated outside this threshold. |
| Can a non-EU installation share information with multiple CBAM declarants? | Yes. After registration and the appropriate access rights are granted, the operator of a non-EU installation can use the O3CI module of the CBAM Registry to upload information and share it with authorised declarants that have been granted access. This can reduce the need to send the same information separately to multiple parties. |
| Can a carbon price paid in the country of origin be taken into account under CBAM? | Yes, subject to the applicable conditions and appropriate supporting evidence. It may reduce the number of CBAM certificates to be surrendered. The carbon price effectively paid should be determined after accounting for any rebates or other forms of compensation. |
| What is the CBAM declaration deadline for goods imported in 2026? | The authorised CBAM declarant must submit the declaration by 30 September 2027 at the latest. This is also the deadline for surrendering the corresponding CBAM certificates for imports made in 2026. |
ARES Vietnam provides audit, certification, validation, and verification services related to environmental management systems, greenhouse gases, and carbon. Companies can contact ARES Vietnam to discuss their existing systems and determine suitable audit, certification, validation, or verification needs.
- Hotline:085.3858.553
- Email:service@aresvietnam.vn
Related news
Greenhouse Gas Inventory Process for Businesses Under ISO 14064-1
Read more

Classification of Import and Export Goods Under Circular 85/2026/TT-BTC: What Should FDI Enterprises Control?
Read more
Control of Measuring Equipment in Manufacturing Plants: What Should FDI Enterprises Consider Under ISO 9001?
Read more
ARES VIETNAM AT THE 2ND MEMBER CONGRESS OF TERM 19 & MID-AUTUMN FESTIVAL GALA
Read more
Liquid Milk Has Passed Testing: What Else Should Businesses Control?
Read more