

What Factors Affect Greenhouse Gas Inventory Costs?
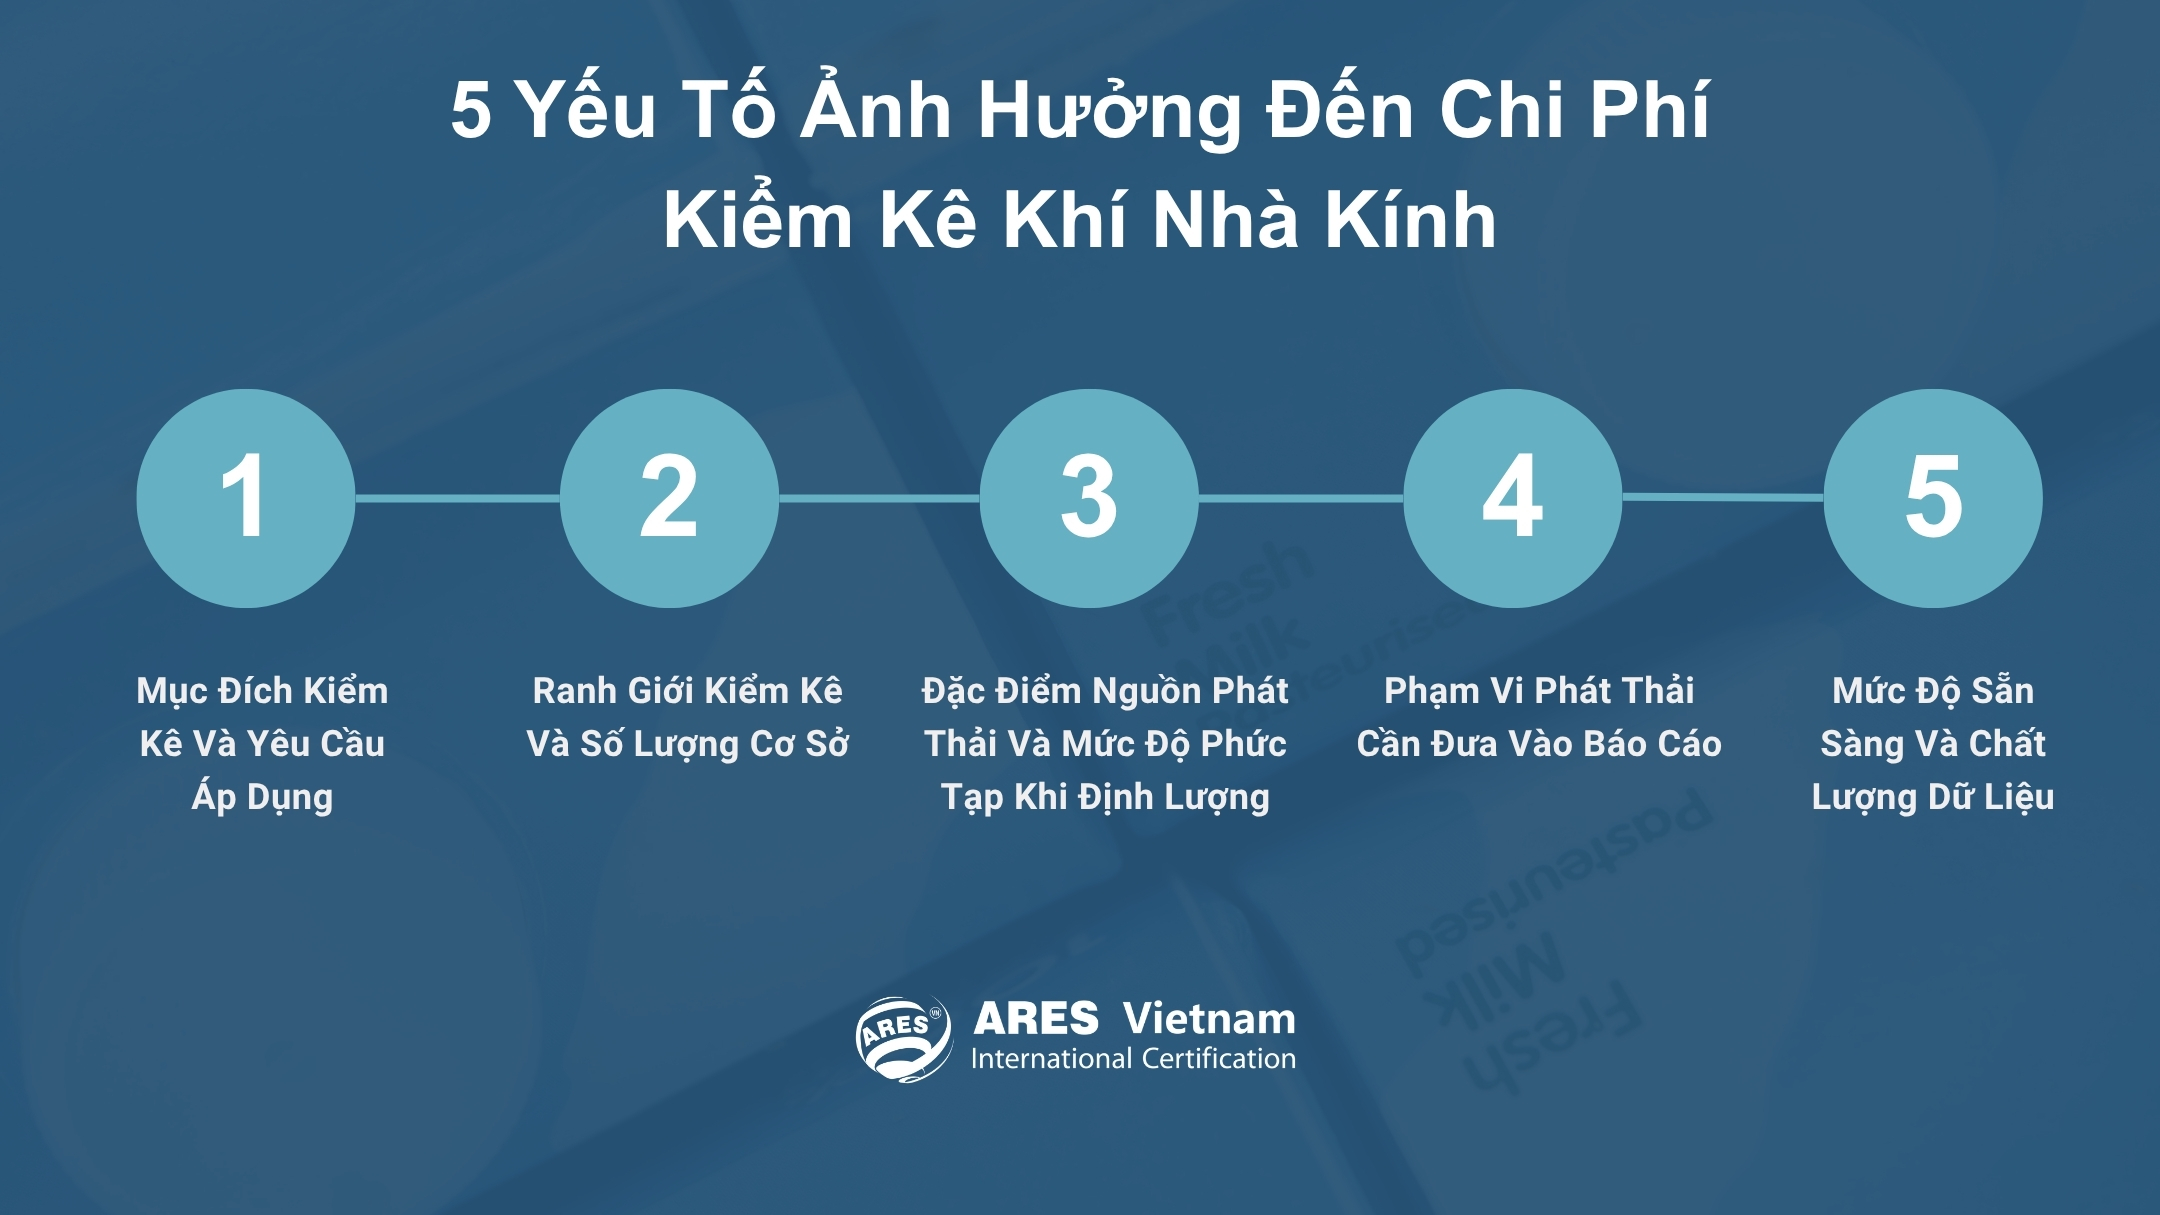
Greenhouse gas inventory costs depend on the purpose of the inventory, inventory boundaries, characteristics of emission sources, the emission scope to be reported, and the company’s data status. Therefore, companies of a similar production scale may still face different workloads and cost levels.
Before setting a budget or comparing quotations, companies should first clarify the scope of work and identify which activities are included in each proposal.
What Does the Cost of a Greenhouse Gas Inventory Include?
The cost of a greenhouse gas inventory project may consist of several components, depending on the service scope and applicable requirements.
| Cost Item | Description |
| Inventory preparation and reporting | Defining boundaries, identifying emission sources, processing data, performing calculations, and preparing reports in accordance with applicable requirements. |
| Internal resources | Time spent by relevant departments providing data, explaining records, and coordinating information processing. |
| Independent verification | Costs incurred when the company or report recipient requires the inventory results to be verified by an independent party. |
Greenhouse gas inventory preparation and independent verification are two separate activities. ISO 14064-3:2019 specifies principles and requirements for the verification and validation of greenhouse gas statements.
5 Factors That Affect Greenhouse Gas Inventory Costs
1. Inventory Purpose and Applicable Requirements
The intended use of the inventory results affects both the content and level of detail required in the report. Companies may conduct a greenhouse gas inventory to meet legal obligations, corporate group requirements, customer requirements, or internal management objectives.
When an inventory is conducted in accordance with ISO 14064-1:2018, the company must meet requirements for quantifying and reporting greenhouse gas emissions and removals at the organizational level. Depending on the applicable requirements, the methodology, documentation, and supporting information may vary.
For companies subject to mandatory greenhouse gas inventory requirements in Vietnam, more information is available in the article Decision No. 42/2026/QD-TTg: Updated List of Facilities Required to Conduct Greenhouse Gas Inventories in 2026.
2. Inventory Boundaries and Number of Facilities
At the organizational level, the organizational boundary determines which entities and facilities are included in the inventory under the selected consolidation approach.
Facilities within the inventory boundary should be assessed in terms of their activities, emission sources, and relevant data. For an organization-level report, results are then consolidated according to the defined boundary.
The number of locations alone does not fully reflect the complexity of the inventory. For example, consolidation is generally more straightforward when facilities use similar technologies, fuels, and data management methods. In contrast, additional work may be required when each facility operates under different processes.
3. Emission Source Characteristics and Quantification Complexity
Different emission sources require different types of data and calculation methods.
For instance, emissions from fuel combustion can often be quantified using fuel consumption data and appropriate emission factors. Meanwhile, some industrial processes may require additional information on raw materials, composition, production output, or material balances.
As a result, the characteristics of emission sources affect the time required for data collection, methodology selection, and calculation.
4. Emission Scope Included in the Report
The emission scope should be defined according to applicable requirements and the intended use of the report. When applying ISO 14064-1, companies need to establish significance criteria and use them to identify relevant indirect emissions for inclusion in the inventory.
For direct emissions and indirect emissions from imported energy, such as purchased electricity, steam, heat, or cooling brought in from outside the organizational boundary, information is usually available in operational records. Other categories of indirect emissions may require information from suppliers, transportation providers, or other parties in the value chain. Consequently, more work may be required to collect and review the necessary data.
For further reference, see the article Greenhouse Gas Emissions Reporting: Understanding Scope 1, Scope 2, and Scope 3 for the GHG Protocol classification and how it differs from the categorization under ISO 14064-1.
5. Data Availability and Data Quality
Data availability and quality directly affect the amount of work required before calculations can begin. Additional preparation may be needed when:
- Data is missing for certain periods;
- Data has not been separated by facility, while the reporting requirement calls for facility-level information;
- Units of measurement vary across records;
- Figures shown on invoices differ from operational records;
- Shared data needs to be separated or allocated according to the inventory boundary or reporting requirements.
When data requires further preparation, companies may need to review, reconcile, standardize, or establish an allocation basis before carrying out the calculations.
Companies that already apply ISO 14001 or ISO 50001 may be able to use existing environmental records and energy use or consumption data. However, these records should first be checked for the relevant reporting period, boundary, and level of detail before they are used in the inventory.
What Should Companies Check When Comparing Greenhouse Gas Inventory Quotations?
Two quotations with different prices may cover different scopes of work.
For example, one service provider may perform calculations based on a dataset already prepared by the company. Another quotation may also include site surveys, data collection guidance, data review, and report preparation. Therefore, these items should be clarified before comparing the total cost.
| Item to Check | Key Point to Confirm |
| Applicable requirements | Which standard, regulation, or report recipient requirement is the quotation based on? |
| Scope of work | Which facilities, activities, and emission categories are included in the quotation? |
| Inventory period | Which reporting period does the quotation cover? |
| Data processing responsibilities | Which party is responsible for reviewing, standardizing, supplementing, or processing the data? |
| Deliverables | Which reports, calculation files, and supporting documents will the company receive? In which language and format? |
| Verification | Is independent verification included in the quotation or priced separately? What is the verification scope? |
| Taxes and related costs | Does the quotation include taxes, surveys, and travel expenses? |
| Additional charges | How are additional facilities, reporting periods, deliverables, or working sessions charged? |
What Should Companies Prepare to Receive a More Accurate Quotation?
The clearer the initial information, the better the service provider can assess the actual workload.
When a company only provides its industry and general scale, the quotation may need to rely on several assumptions. As a result, adjustments may be required after the survey or scope review.
Before requesting a quotation, companies should prepare:
- The number and locations of facilities to be included;
- Industry, products, and main production processes;
- Expected inventory period;
- Information on electricity and fuel use, as well as known major emission sources;
- Current data status;
- Intended use of the report;
- Required completion timeline;
- Independent verification requirements, if applicable.
At this stage, the company can begin with the available information about its main emission sources. Any remaining details can be further identified during the survey and scope discussion.
Frequently Asked Questions (FAQ)
| Question | Answer |
| Does a larger total volume of emissions mean a higher inventory cost? | The total volume of emissions and the workload required for the inventory are two different factors. A company with high emissions, concentrated emission sources, and complete data may require less data processing than a company with numerous dispersed sources or data that requires additional review and supplementation. |
| Are software or measurement equipment costs included in greenhouse gas inventory costs? | This depends on the project scope. Data management software, measurement equipment, or monitoring system upgrades may be treated as separate investments when the company needs them to support data collection and management. These items should therefore be identified separately from the cost of conducting the inventory. |
| Can a company use records from the previous inventory period for the next period? | Yes. Companies can reuse templates, emission source lists, and methodologies when they remain suitable. Activity data should be updated for the new inventory period. At the same time, emission factors and any changes in facilities, activities, or reporting requirements should also be reviewed. |
Companies planning a greenhouse gas inventory budget can send ARES Vietnam information on their facilities, inventory period, current data status, and required deliverables. Based on this information, ARES Vietnam can discuss the scope of work and provide an appropriate quotation.
- Hotline: 085.3858.553
- Email: service@aresvietnam.vn
Related news
Emissions Data & CBAM: 5 Practical Questions from Factory Operations
Read more

Greenhouse Gas Inventory Challenges: What Data Should Businesses Prepare?
Read more
ARES Vietnam Conducts ISO 45001:2018 Surveillance Audit at A&J (VIETNAM) CO., LTD.
Read more
Rice Export and Import Business Under Decree 365/2026/ND-CP: What Should Enterprises Control?
Read more
ARES Vietnam Verifies Greenhouse Gas Report under ISO 14064-1:2018 at GE LAN Vietnam
Read more